Download this week’s full edition!
Despite a volatile September marked by Middle East conflict driving oil and diesel prices higher, a Fed rate hike, and rising long-term Treasury yields, the S&P 500 ended nearly flat thanks to strength in mega-cap tech stocks—even as the average stock in major indexes fell about 5%.
What caught our eyes this week
A memorable September
At -0.35%, the S&P 500 was roughly flat in September. That wouldn’t typically be a monthly return to celebrate, but it still felt like an achievement given everything the markets absorbed during the month. As the conflict in Iran evolved, oil prices marched toward $100 per barrel before backing down into the $90 range. Diesel prices rose above $6 per gallon nationally, an all-time high. The Federal Reserve delivered its first rate hike in years and signaled that more may follow. Long-end US Treasury yields finally broke out of their three-year range, with 10- and 30-year rates reaching multidecade highs. Yet the S&P 500 stayed flat, largely thanks to resurgent leadership from the Magnificent Seven and the broader AI trade, which had floundered for much of the year. Beneath the surface, breadth deteriorated meaningfully, with the “average” stock in the S&P 500 and Russell 2000 small-cap index both down about 5%. Looking ahead, we’d be remiss not to note that seasonality tends to favor fourth-quarter returns, particularly after midterm elections.
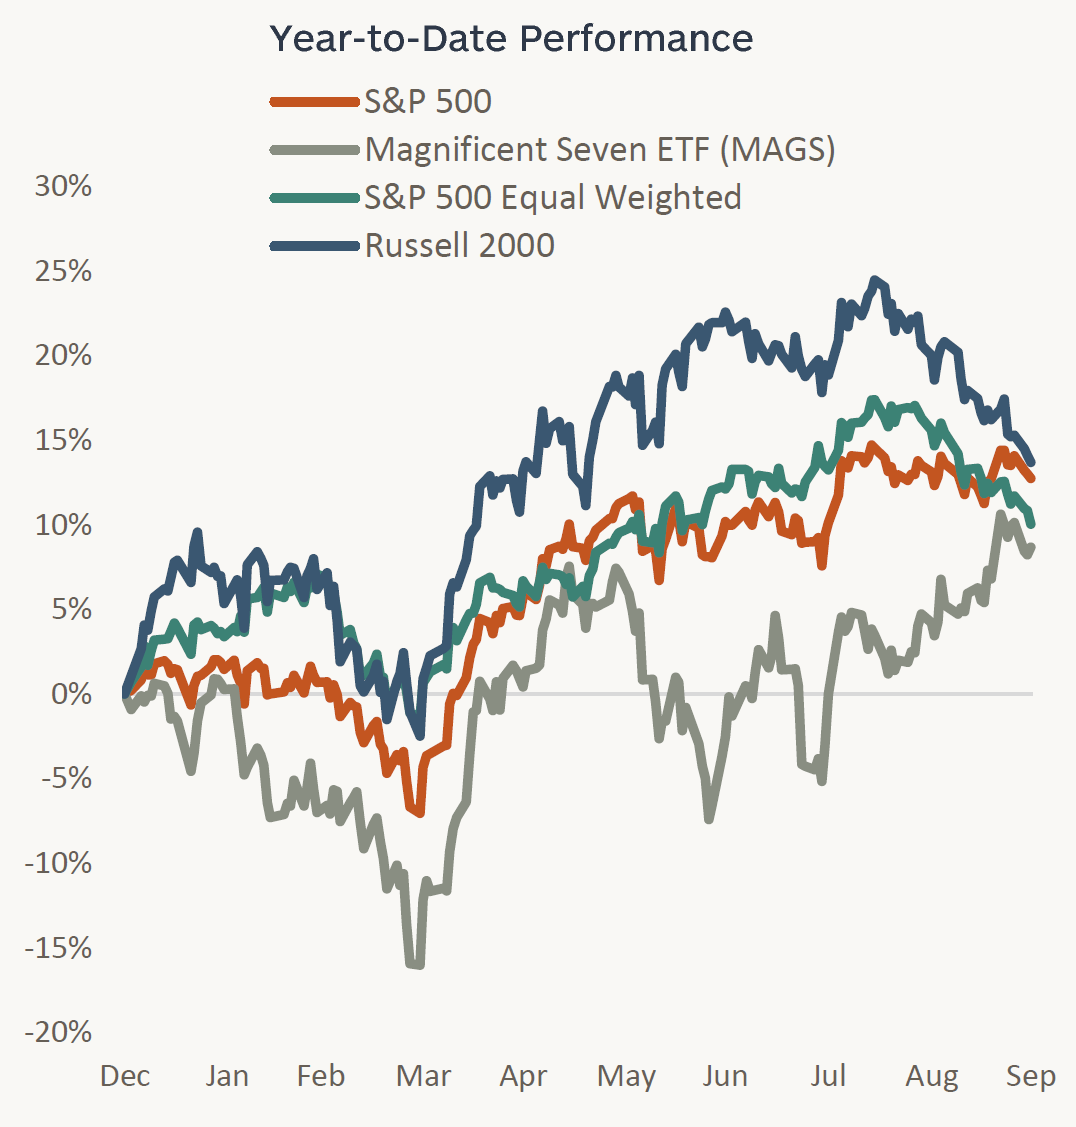
CHART OF THE WEEK: Cerity Partners, YCharts, 1/1/2026–9/30/2026
Past performance does not guarantee future results.
Please read important disclosures here.