Download this week’s full edition!
After midterm races centered on curbing data center development helped trigger a sharp market sell-off, the AI build-out is likely to be constrained at the margin rather than halted, since roughly 600 campuses already under construction will proceed while the 2,600 still in planning may face slower permitting or simply relocate.
What caught our eyes this week
The latest tremor in the AI trade
Seismic shifts in Washington, DC, gave way to seismic shifts on Wall Street last week, with the S&P 500 falling 4.4% on Thursday for its worst day since April 2025. The primary link between midterms and markets is AI. Curtailing data center development was a key speaking point for many races, including data center hotbeds like Texas, Georgia, and Ohio. The PHLX Semiconductor index, which had already been taking it on the chin, fell another 12% last week. Moves like this convey sentiment that the AI infrastructure build-out is about to grind to a halt. We think the path forward is a bit more nuanced. It appears development will proceed as expected for the nearly 600 data center campuses already under construction nationwide, which alone will represent a 40% increase from the existing base in operation. For the 2,600 more in the planning stage, permitting may indeed be slower, more difficult, and more expensive. Or it may just move to where it’s more welcome. Details are scarce, and likely will be for a while as
politicians who seized the opportunity for a good sound bite will now grapple with the economic and tax revenue trade-offs of data centers in their jurisdictions. Overall, a supply-constrained market may get more constrained at the margin, but that hardly feels like the death knell for the AI ecosystem.
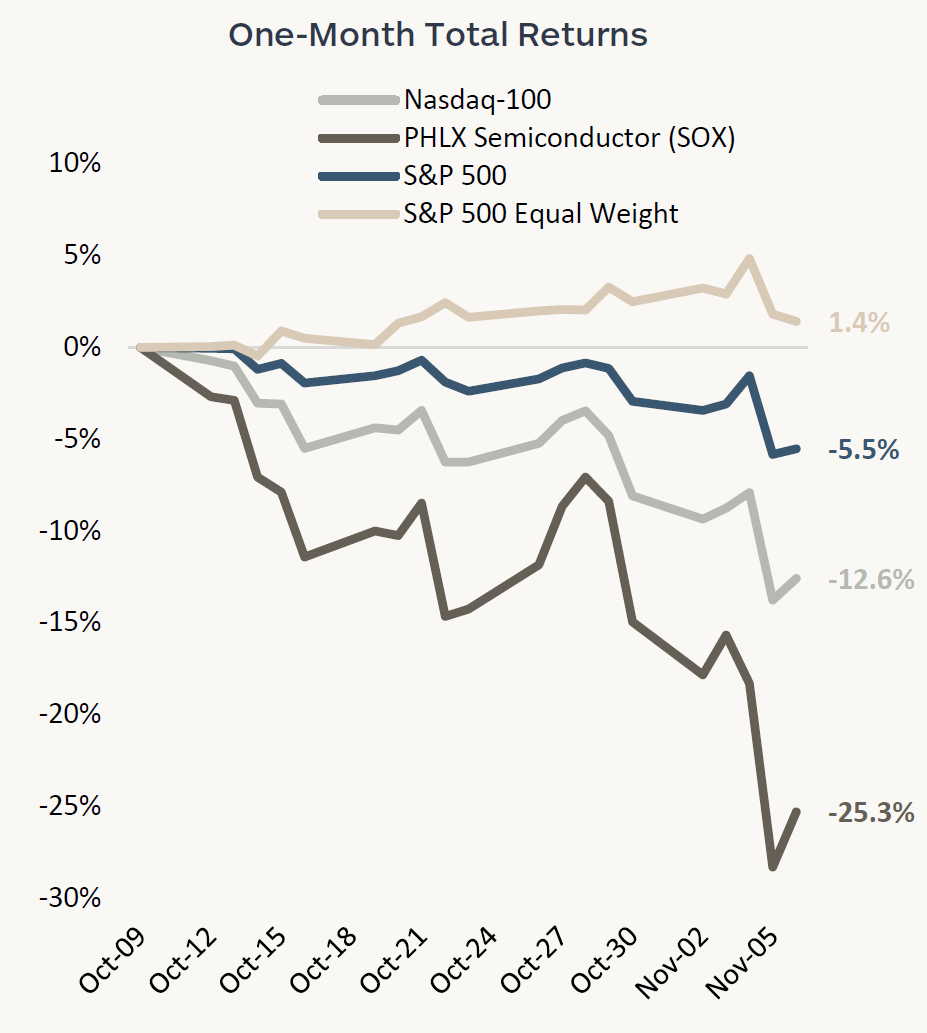
CHART OF THE WEEK: Cerity Partners, Cleanview, YCharts, 10/9/2026–11/6/2026
Past performance does not guarantee future results.
Please read important disclosures here.