Download this week’s full edition!
Long-end US Treasury yields have broken out of their five-year range primarily due to strong nominal and real GDP growth, and the current level of yields appears to be a normal reflection of this economic backdrop rather than a sign of crisis.
What caught our eyes this week
A powder keg of upside catalysts
Long-end US Treasury yields finally broke out of their range from the past five years. The list of upside catalysts for interest rates is lengthy, including sticky inflation, elevated energy prices, Federal Reserve (Fed) rate hikes, a flood of new bonds from hyperscalers, competitive yields globally, and concerns of fiscal sustainability. Another simple explanation is the one we put the most weight behind: strong economic growth. Nominal GDP (i.e., before inflation) is growing by over 6% year over year. With the Atlanta Fed estimating 5% real (i.e., after inflation) GDP growth for Q3, it looks like this environment is set to continue. This was corroborated last week by the S&P Global composite PMI measure of economic expansion, which hit its highest level since July 2021. To us, the moves we’re seeing in yields still fall more in the camp of normalization than crisis. In fact, in a simple regression of nominal GDP growth to 10-year Treasury yields, the current data point sits just about on the regression line. In other words, Treasury yields are just about where they should be for the current economic backdrop.
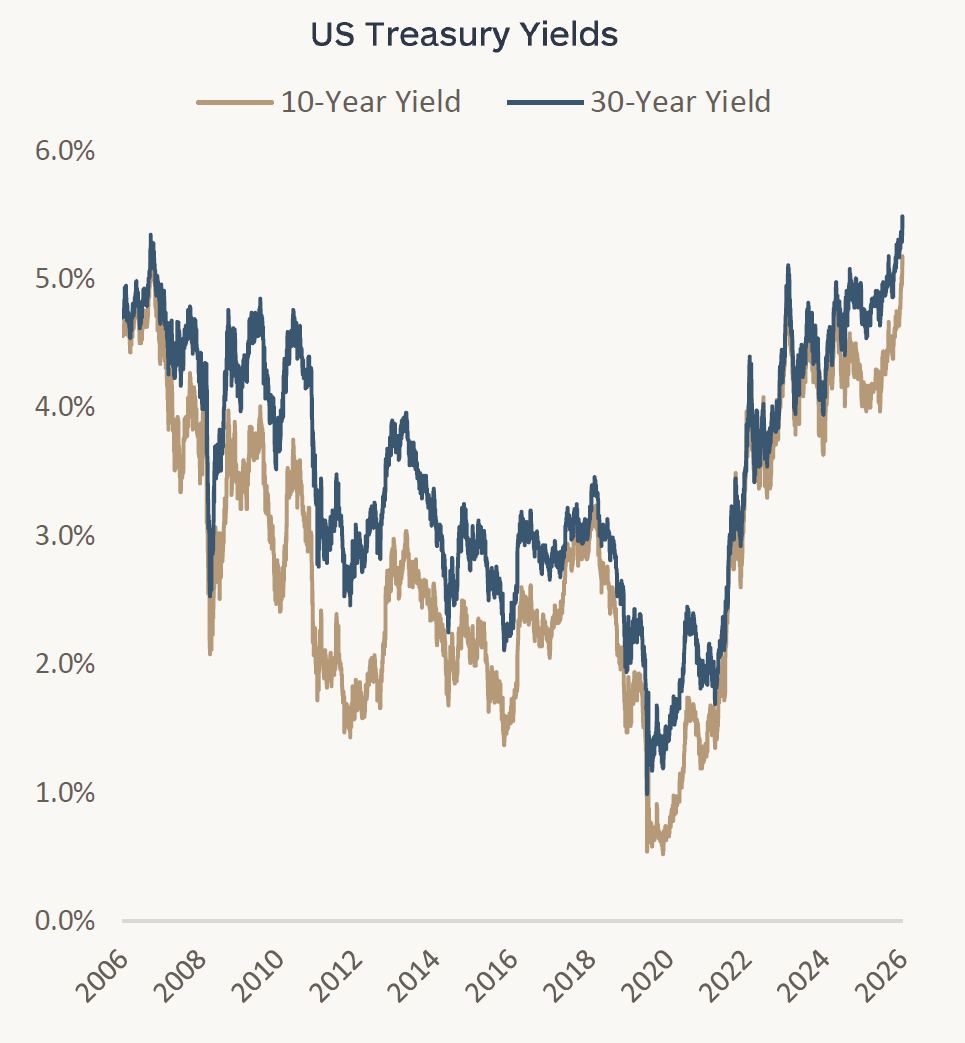
CHART OF THE WEEK: Cerity Partners, YCharts, 9/25/2006–9/26/2026
Past performance does not guarantee future results.
Please read important disclosures here.