Download this week’s full edition!
Nearly six weeks after market highs, the pain has been concentrated in AI-related stocks, which are now in a bear market, while most other industries and the average stock have held up well.
What caught our eyes this week
Rotation, rotation, rotation
It’s been a tale of two markets for large-cap stocks. We’re now nearly six weeks out from the latest highs for the S&P 500 and the Nasdaq-100 indexes. Since then, we’ve seen some pain, but it’s been highly concentrated in AI-related stocks and industries. The semiconductor and equipment industry, at one point ahead of the broader index by 50% year to date, has now given back nearly all its relative outperformance. With a Goldman Sachs basket of broader AI stocks down 30% from its peak, it’s safe to say we are in an AI bear market. Meanwhile, it’s been business as usual for the rest of the market, with 80% of the industries in the market up since the high on October 6. The average stock, as represented by the S&P 500 Equal Weight Index, is up 17% on the year, 4% higher than the high in its market cap–weighted counterpart. Even within the tech-heavy Nasdaq-100 index (currently in a correction), roughly half of the stocks are up, largely pharma, biotech, software, and other non-AI industries. There has been steady concern for the past few years that if the AI capex trade were to stumble, it could drag the rest of the market down with it. Fortunately, that has not been the case so far.
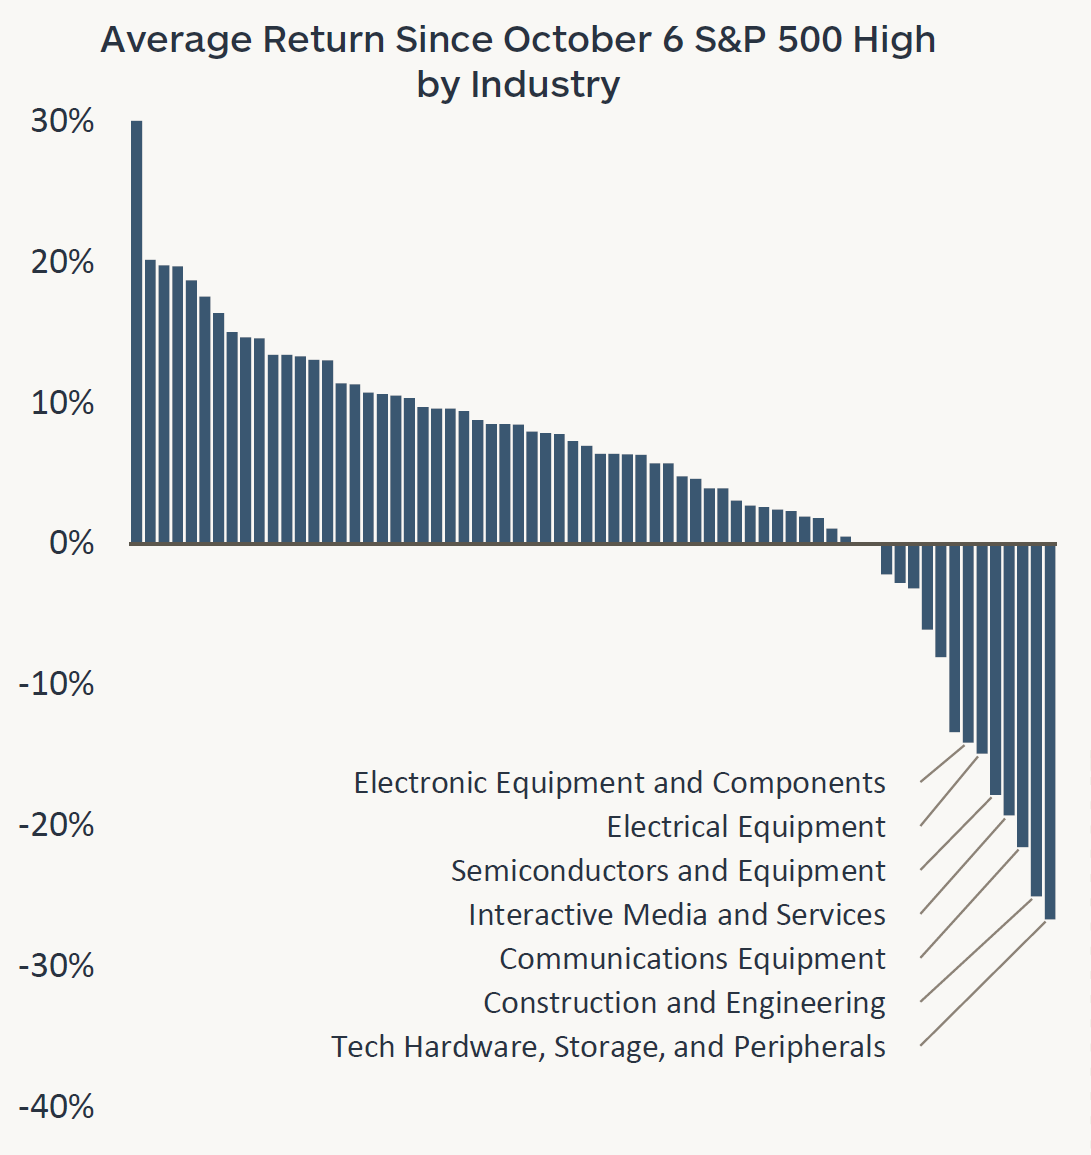
CHART OF THE WEEK: Cerity Partners, Cleanview, YCharts, S&P US. Equal-weighted average of S&P 500 constituents by GICS industry, 10/06/26 to 11/13/26, including dividends
Past performance does not guarantee future results.
Please read important disclosures here.